UK Gambling Commission Reports 4.4% Rise in Annual Yield to £17.5bn as Online Growth Offsets Shrinking High Street

UK gambling revenue reached £17.5 billion in the financial year running from April 2025 to March 2026, according to newly published Gambling Commission figures. The total marks a 4.4% rise on the previous 12-month period, driven largely by continued momentum in online betting and casino play.
In This Article
The regulator’s Industry Statistics annual report, released alongside its Quarter 4 breakdown (January to March 2026) and the latest wave of the Gambling Survey for Great Britain (GSGB), paints a picture of a market shifting decisively toward remote channels even as its physical footprint continues to contract.
Online Growth Offsets High Street Decline
Stripping out all lottery activity, gross gambling yield (GGY) came to £13.2 billion, up 4.7% year-on-year. That growth was almost entirely attributable to remote gambling, which stood in sharp contrast to a land-based sector that, while still growing modestly overall, is losing physical premises at a steady clip.
Remote casino, betting and bingo activity generated £8.3 billion in GGY, a 6.9% increase that made it the standout performer of the year. That figure alone accounted for roughly 63% of total non-lottery industry yield, underlining how central online play has become to the sector’s overall health.
As of 31 March 2026, the Commission counted 2,154 licensed gambling operators, a 1.1% decline on the year before. Despite fewer operators, the number of separately licensed gambling activities they held edged up 0.4% to 3,097, suggesting a market of fewer, more diversified operators.
Remote Casino and Betting Breakdown
Within the remote category, online casino alone was worth £5.7 billion over the 12-month period, of which £4.8 billion came from slots. Remote betting brought in £2.4 billion, led by football at £1.2 billion and horse racing at £769.3 million. Remote bingo trailed at £147.8 million.
The most recent quarterly snapshot, covering January to March 2026, reinforced the trend: online verticals generated £2.2 billion in that quarter alone, with remote casino accounting for 68.3% (£1.5 billion) of that total. Total industry GGY for the first quarter of 2026 came to £4.4 billion including lottery revenue, or £3.4 billion when lottery activity is excluded.
Land-Based Sector and Premises Data
The land-based sector — adult gaming centres (AGCs), betting shops, bingo halls and casinos combined — produced £4.9 billion in GGY over the year, a 1.1% increase. But the underlying premises count tells a different story: the UK’s physical gambling estate shrank by 2% to 8,081 locations.
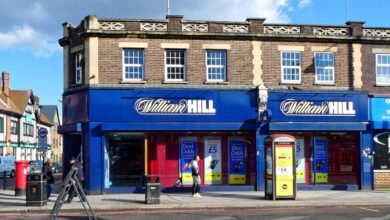
Betting shops bore the brunt of the decline, falling for a twelfth consecutive reporting period to 5,617 outlets, a drop of 3.6% that represents a net loss of 208 shops year-on-year. Major retail operators including William Hill and Betfred have each shuttered hundreds of shops over the past year as they recalibrate their high street presence.
Non-remote betting revenue came in at £2.4 billion, down 3.3%, while non-remote casinos held roughly steady at £933.9 million, up 0.4%. Non-remote bingo was a bright spot for physical venues, rising 8.2% to £703.8 million.
Gaming machines in arcades generated £800.1 million, up 10.7%, with AGCs contributing the bulk of that at £761.4 million, an 11.3% increase. Across all settings, gaming machines contributed £2.7 billion to overall GGY, a 4.3% uplift. The Commission recorded 191,804 gaming machines in licensed premises during the final quarter of the reporting year.
National Lottery and Society Lotteries
The National Lottery posted ticket sales of £7.9 billion, up 0.9%, while prize payouts dipped slightly by 0.6% to £4.5 billion. Contributions to good causes rose 2.8%, landing at an estimated £1.6 billion to £1.7 billion for the year.
Large society lotteries also grew, with ticket sales up 5.7% to £1.2 billion, prize payouts up 6.1% to £335.6 million, and good-cause contributions up 2.8% to £498.5 million — a segment that continues to expand steadily alongside the National Lottery.
Gambling Commission on Market Drivers
Ben Haden, the Gambling Commission’s Director of Research and Policy, cautioned against reading too much into any single data point. “The market shifts that we see in industry data trends, and this year is no different, are complex and will be down to a mix of factors that need more than one source to unpick,” he said. “I welcome our capacity to publish industry data alongside the Gambling Survey for Great Britain to encourage and assist in the consideration of key questions from these different perspectives.”
That framing reflects the Commission’s broader approach of pairing raw revenue figures with behavioural survey data, rather than treating GGY trends in isolation.
Participation Trends from the GSGB Survey
The Commission’s companion Gambling Survey for Great Britain, based on responses from 5,277 adults surveyed between January and May 2026, found gambling participation patterns largely unchanged from previous years. Around 49% of respondents said they had gambled within the past four weeks.
Excluding those who only played lottery draws, participation stood at 28%, implying lottery-only players made up roughly 21% of the adult population. Online gambling participation over four weeks reached 39% overall (16% excluding lottery-only players), while in-person participation was 29% (18% excluding lottery-only players).
The most popular non-lottery activities were scratchcards (13%), betting (10%) and online instant win games (8%). Betting activity skewed heavily male, with 16% of men gambling on betting compared to 4% of women. By age group, overall participation peaked among 45- to 64-year-olds at 56%-59%, while excluding lottery play, the highest participation shifted to 35- to 44-year-olds at 35%.
Respondents most commonly cited the prospect of large winnings and general entertainment as their motivations for gambling, and 42% reported feeling positive about their most recent gambling spend.
Looming Policy Changes Under PM Burnham
The figures land against a backdrop of potential regulatory change. Prime Minister Andy Burnham has recently proposed a package of measures that would repeal the long-standing “aim to permit” rule governing betting shops and 24-hour slot machine arcades across Great Britain — a rule that currently creates a presumption in favour of granting planning permission for such venues.
Under the proposal, AGCs in England offering round-the-clock access to gambling machines would instead need to secure specific planning approval, a change that could slow the opening of new venues even as existing betting shop numbers continue to fall.
Burnham is also weighing an increased tax on gaming machines, based on a proposal put forward by the Social Market Foundation. Any such move could surface in the government’s upcoming autumn budget, adding a further layer of uncertainty for land-based operators already contending with a shrinking physical footprint and rising online competition.